Friday, October 29, 2010

Where does hard-headedness end and nastiness begin?

I have been arguing with a friend of mine, someone whose work I admire and whom I like personally, about the election.  In one email, he wrote to me:

All this administration has done, in effect, is additionally regulate banks and businesses (in the middle of a deep recession) and transfer resources from high skill to low skill.  That's what the health care plan and the extension of unemployment benefits has done.
There are a few large presumptions here: that wealth is a function of skill, and that skill is the most important criterion for determining whether one "deserves" resources.   I have no doubt that there is a strong correlation between skill and wealth, but I also have no doubt that a regression where wealth is on the left hand side and skill is on the right would have a large residual.

But even if skill translated perfectly to wealth, I am uncomfortable with the idea that the unskilled are unworthy of having a decent standard of living, particularly in a country as rich as the United States.  I also think that income distribution data from OECD calls into serious question whether rewarding the "highly skilled" leads to better outcomes for the lower income parts of society.  Thus I recoil at the idea that extending unemployment insurance periods in times when there are far more job seekers than jobs is a good idea.

That said, the hard-headed aspects of economics do lead to important insights.  For example, when the country is at full-employment (or something like it), the duration of unemployment insurance should be limited, because we do want people to work.  Similarly, we should always make it better for people to work than to receive government assistance.  I could also go on about the evils of rent control, etc.

This is where I feel conflicted about my discipline on a regular basis.  So much of what we put out there strikes me as being on its face inhumane and arrogant.  Yet I would hate to see what policy would look like in our absence.

Thursday, October 28, 2010

Sampling

If my friends were a representative sample of the US population, there will be 30 million people at the Rally to Restore Sanity. (Putting the subjunctive together with the future tense sure is awkward!).

Wednesday, October 27, 2010

The real reason why a foreclosure moratorium would be a bad idea

I was on Marketplace the other day debating Mike Konczal about whether a foreclosure moratorium  would be a good idea.  I took the no position for two reasons:

(1) A moratorium would slow down the eventual resolution of the housing crisis;

(2) A moratorium would add yet another level of uncertainty about the ability to foreclose going forward, which would discourage the private sector from returning to the mortgage market.  If lenders can't take away the houses of people who don't make their payments, they will not advance mortgage money in the first place.

But last night it occurred to me why I have such a visceral reaction to such things as moratoriums: they strip property rights without due process.  If a borrower agrees to repay a mortgage, and everything about the mortgage is legitimate, and the borrower ceases to make payments, the lender has a property right to take the house.

I am at times a card-carrying member of the ACLU, because I think the rule of law and due process should apply to everyone.  Many lenders have behaved badly and appear to still be behaving badly.  That doesn't mean that all of them should lose their well-defined rights--even temporarily.

Monday, October 25, 2010

Why to avoid motorcycle riding in India


Hannah in Bodh Gaya: the most dangerous thing you can do » North by Northwestern

I

saw someone die in the street last night.

During orientation, Robert explained the five Buddhist Precepts to us, and he explained why our experience and that of others would be better if we agreed to follow them during our time here. Then he said that if we broke one, we shouldn’t beat ourselves up, but that we should try not to do it again. When a few students were caught drinking and smoking on the roof, he said at lunch that he’d heard about it, and that if we had any intoxicants in our room we should go get them and flush them down the toilet. He didn’t say to go get them and bring them to him. He understands that he can’t make us do anything.

The only thing that he forbade expressly was riding motorcycles.

“Riding a motorcycle in India is the most dangerous thing you can do,” he said. “There is no trauma ward. If you get into an accident, everyone will stand and watch while you bleed to death in the street.

I saw the crowd before I saw the body. I was walking with a couple of French people I’d met the night before. They saw the crowd and didn’t wish to walk that way. One man told me it was OK for us to pass, so I went because otherwise I would be late to mediation. For just half a second I saw the man lying exactly on his back in a pool of blood with a thick stream of blood draped across his face and body. It could not have been more red. His motorcycle was behind him. I turned my head away and touched the wall next to me, but the image has not left my mind. This body was not like a body prepared for cremation in Varinassi. They were supposed to be dead. This man was still fresh. He should have been alive. At the moment I saw him, maybe he was alive.

I walked back the way I’d come and saw my fellow students coming toward me in rickshaws. I looked at them and said “there’s a dead man in the street.” I expected them to stop or something, but the rickshaws just went past. Only Wanda and Heidi got out. I didn’t want to walk alone, so I had to walk past the same place to catch up with them. The body was being carried up the hill on a woven stretcher, and I had to see the pool of blood mixed in the gravel and rainwater again as I walked past.

When we got to mediation we were having a group photo taken. We had to wear our Zen robes. I thought “I can’t figure out the strings on these robes, I just saw a dead man,” and “I can’t smile for this photo, there was so much blood,” and “I can’t get up for walking mediation, he was lying right on his back like he was in bed,” but I managed to do all those things anyway.

It was our final meditation session in the Japanese temple, so afterward one of the monks spoke to us. He told us that “Arigato” means more than thank you in Japanese. It means, these circumstances were difficult to come by, and we are so happy that you can be here. You are not just thanking the person you are speaking to, but you are thanking every circumstance that lead you to be together. He said we should all call or e-mail our families to say “arigato”. He said that it might confuse them, but he didn’t care. Maybe it’s wrong, but it’s true that seeing death like that makes you understand how rare it is that so many of the people you love are still healthy and fine. Arigato.

Thursday, October 21, 2010

The Fannie-Freddie Problem is not as severe as the headlines would suggest

Page 10 of the FHFA report, gives forward expected losses under three scenarios.  The third is really awful--it assumes a further reduction in house prices by 1/4, which would be a lot.  But under the other two scenarios, the net cost to taxpayers (draws less dividends owed to Treasury) would be $6 to 19 billion.  This is real money, but hardly cataclysmic.  It does suggest that the vast majority of the losses are already behind us.

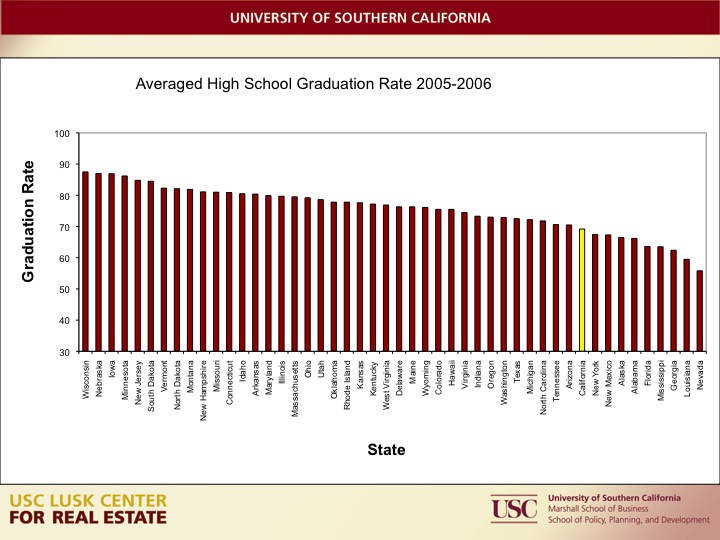
Ten Slides on California (and the other 49 States)


Wednesday, October 20, 2010

Second Annual UCI-UCLA-USC Urban Research Day

2nd Annual UCI-UCLA-USC Urban Research Day
October 22nd, 2010
Ralph & Goldy Lewis Hall 100


8:30 am
Continental Breakfast

Session 1
9:00 am - 11:00 am

Kerry Vandell (University of California, Irvine)
"
Tax Structure and Natural Vacancy Rates in the Commercial Real Estate Market: Can Tax Incentives Cause Overbuilding in a World of Stochastic Prices”

Discussant:
Gary Painter (University of Southern California)

Stuart Gabriel
(University of California, Los Angeles)
"Housing Risk and Return:  Estimates of a Housing Asset Pricing Model"

Discussant:
Xudong An (San Diego State University)


Break   11:00 am – 11:10 am

Session 2
11:10 am – 12:10 pm

Ryan Vaughn (University of California, Los Angeles)
“Strategic Foreclosure:  An Empirical Assessment of
Strategic Behavior by Lenders in the Mortgage Market”

Discussant:
Chris Redfearn (University of Southern California)


Session 3
1:15 pm – 2:15 pm

Richard Green (University of Southern California)
“Surfing for Scores:  School Quality, Housing Prices, and the Changing Cost of Information” with Paul Carrillo and Stephanie R. Cellini

Discussant:
Matthew Kahn (University of California, Los Angeles)

Break   2:15 pm – 2:25 pm

Session 4
2:25 pm – 3:25 pm

Jenny Scheutz (University of Southern California)
“Is the 'Shop Around the Corner' a Luxury or a Nuisance?The relationship between income and neighborhood
retail patterns” with Jed Kolko and Rachel Meltzer

Discussant:
Jan Brueckner (University of California, Irvine)

Break
   3:25 pm – 3:35 pm

3:35 pm – 4:30 pm

Session 5
Marlon Boarnet (University of California, Irvine)
“ Land Use and Vehicle Miles of Travel in the Climate
Change Debate: Getting Smarter than Your Average
Bear”

Discussant:
Lisa Schweitzer (University of Southern California)


Dinner              6:00 pm
Location           CafĂ© Pinot


Minutes vs Stress

The Texas Transportation Institute says that the place I live now, Los Angeles, and that I lived just before LA, Washington, have the worst traffic in the country (they actually rank one and two), where worst is defined as average minutes spent in bad traffic per day.  

Today was a bad day in LA--it rained, and people just don't know how to deal with that here.  But for some reason, I found commuting by car in DC to be far more frustrating.  In both cities, the distance between my home and office was about the same.  As it happens, I hated driving in DC so much that I took Metro to work nearly every day, and the total Metro commute was about 50 minutes one way (including walking).  On the other hand, the walk from my house to the Bethesda Metro station and from Dupont Circle to my office in Foggy Bottom was quite pleasant.

But back to the point--somehow driving in LA seems far less stressful to me than driving in Washington.  Maybe it's just that the radio stations are better....

Sunday, October 17, 2010

Read Yves Smith

Yves Smith was ahead of the Times and the Journal (and so far as I can tell, everyone else) on the foreclosure mess.  I learn a lot from her about what is happening with mortgage backed securities, and I teach students about them for a living.

Monday, October 11, 2010

I wish I could give credit where it is due

I was in Madison a few weeks ago, working on the second edition of my book with Steve Malpezzi.  We took an hour out one afternoon to gossip about Nobels with Don Nichols, Dan Bromley, Werner deBondt and Bob Krainer.  One of these gentlemen forecast Peter Diamond as this year's winner, but I can't remember who.  Such prescience....

Sunday, October 10, 2010

Greg Mankiw forgets about the income effect

Professor Mankiw says he can afford higher taxes.  For that I give him credit.  But he also says that higher income taxes might keep him from writing his New York Times column.   He then implies that higher taxes will generally keep people from working.

This is the substitution effect--because leisure becomes relatively cheaper, people consume more of it.  But higher taxes also reduce after-tax income (obviously), so in order to maintain living standards, one might decide to work more in the face of higher taxes.  This is called the income effect.  I can speak for my household--our after-tax income is more than sufficient for our "needs," but if we were taxed more, we might have to work more to satisfy these "needs."

It is an empirical question as to whether within certain ranges of tax rates, raising taxes increases or reduces effort.  Theory gives us an ambiguous answer.  (h/t Mark Thoma).

Saturday, October 09, 2010

If NJ Governor Christie wanted to run New Jersey like a business...

...he would not have vetoed the construction of a new rail tunnel from NJ to NY.  It is hard to imagine that this is not a positive NPV opportunity.

Monday, October 04, 2010

A little data exercise on housing affordability

I just had two graduate students here at USC--Sarah Mawhorter and Ray Calnan--find 25th percentile gross rent and 25th percentile income for renters for the 50 largest MSAs in the United States using 2008 American Community Survey Data. If "affordable" means that every household has the opportunity to spend less than 30 percent of gross income on rent, not a single one of the 50 largest MSAs is affordable for renters at the 25th percentile. The least affordable is Miami, where 25th percentile rent-to-25th percentile income is in excess of 50 percent; the most affordable is Kansas City.

Saturday, October 02, 2010

Favorite Line of the Week (h/t Bob Van Order)

The difference between a theorem and a tautology is how fast you think.

The William Cohan fallacy

William Cohan the other day complained that Elizabeth Warren fallaciously claimed borrowers did not know what they were getting themselves into when they took out exotic loans. Cohan suggests instead that the vast majority of borrowers knew what they were signing up for when they took out exotic mortgages.

This was certainly the case for some borrowers (particularly speculators), but I am not sure "vast majority" is correct. Understanding the intricacies of, say, a pay-option ARM requires a degree of mathematical sophistication that I would guess is beyond the capabilities of many borrowers. My former GW colleague Vanessa Perry has found that many borrowers do not understand anything about credit beyond their next monthly payment. In the case of pay-option ARMS, this payment was often low relative to income and stayed low for some time, so a potential borrower/homebuyer could be "advised" by a mortgage broker lender and/or real estate broker that an expensive house was indeed "affordable."

Should such borrowers have known better? I don't know. I do know that even though I really wanted to dunk a basketball, it was never going to happen, because I am short and can't jump. Similarly, no matter how much they try, there will be potential borrowers with generally good life skills who will never be able to understand an amortization schedule, and who are susceptible to a good sales pitch. To suggest such people are "responsible" for their plight is akin to suggesting that I am "responsible" for never being able to dunk a basketball.

Might Elizabeth Warren's idea of sufficient consumer protection go too far? Sure. But the events of the past eight years or so strongly suggest to me that consumer protection was insufficient.

Lisa Schweitzer on Transportation funding

She bring nuance to an issue that is often argued about with slogans (go to her post for graphs).


One of the common arguments I hear is that transit is underfunded. Now, this is a subjective question. For those who believe that having transit is absolutely vital to cities, no amount would be enough. So that’s not the point.

The other argument that I hear is that we spend too much on highways rather than transit. Again, subjective. There’s no way to suss this question easily enough for a blog post.

But we can take a look at what people seem to believe is a disparity in funding.

This is the graphic you are most likely to see when we discuss differences between highway and transit funding:

Ok, so of the total, highways get about 55 to 60 percent and transit gets 17 percent on average over the time period, but by the end of the time period, transit’s share has risen to about 20 percent and highways has gone to about 54 percent.

So that’s a pretty big difference in funding. But when you factor in the passenger miles served, the calculus changes. In the following graphic, I have assigned 100 percent of the spending on highways to passenger cars–a major overstatement, but it serves the point. It’s an overstatement because highways also serve trucks (a big deal), motorcycles and some transit (less of a big deal.)


My transit advocate friends will patronize me at this point and lecture me about how I’m not factoring in the external costs of the cars–and that’s true.

But I am not sure that external costs are relevant to expenditure fairness. Whether we factor in external costs or not is relevant to tax policy, for sure, but it’s probably not relevant to the budget equity arguments often made. It’s one thing to talk about optimum investment, which would require marginal social cost: it’s another to try to figure out if transit exists is “David” to auto’s “Goliath”.

Here, we’re trying to figure out if transit riders are getting the shaft. Are they getting the shaft (the transit advocate side)? Or are they rolling in dough they don’t need (the Reason foundation argument)?

This is one of the few times I actually might believe the apples and oranges arguments about comparing. Transit is in a building stage, but highways, for the most part, are in the maintenance phase. We could argue ourselves in circles: to reach investment parity, we’d need to double the transit numbers per passenger mile, etc, etc.

I just don’t know what I think. I need to fiddle with the numbers more.

All these data are from BTS, btw.

Hannah Green blogs from an NGO School in India

She writes:


On Tuesday afternoon, we could either take a nap or go to the Pragnya School, a K-10 NGO school in the village. I said that I wouldn’t go and got into bed, only to realize that I was not really committed to napping. My roommate Christina said that she would go but decided that she was too tired. We sat indecisively on the daybed outside our room, and Jesse said, “Come on, we’re going!” and I said “ugh” and we left.

Outside the Vihar gates, eight of us piled into a single autorickshaw. As soon as the rickshaw got going, I was glad that we hadn’t stayed in. The driver saw that we were having fun and put on some Indian pop. We grinned and jerked our heads to the music and felt the breeze coming in through the bars that held the ceiling to the floor. Music isn’t allowed in the Vihar, although we can hear it from the pujas outside all the time (and we’re allowed iPods). Still, we could never listen together like we could in the rickshaw.

When we arrived, we were surprised to find an assembly waiting for us. Girls with plaits in their hair and uniforms filled rows of benches facing a concrete stage with staircases set in three corners, in very Indian style. There were boys in the audience, too, but fewer of them. Sister Shoba, who wore a conservative pink sari and a large crucifix, showed us to a group of folding chairs in the shade.

The first dance was for the Goddess Dergah, which surprised me because of Sister Shoba’s crucifix. There were many dances. The small girls did a dance for the sun god with a lot of dainty marching and raised arms. Their movements were sweet and easy, even when they moved out of step. The boys did wild acrobatic dances which the girls’ clothing and cultural boundaries would not have allowed. In one dance five boys wore camoflage hats to show that they were soldiers in Pakistan. They died dramatically, doing backlfips and jerking along the ground. When they came back to life, one boy bent over backwards and kissed the ground between his feet. In the dance for the goddess Dergah, a teenage boy danced alone wearing only low-rise jeans and a white kerchief around his waist. He danced with two real torches, twisting his body and tracing his torso with the flames. I was a little envious of all the dancing. In America, you don’t learn to move that way. I also felt that it had been too long since I’d danced because dancing isn’t allowed at the Vihar.

When all the organized dancing was over, one girl got up and danced by herself, then the boys got up and danced and tried to take us with them. At first we hesitated. Robert had told us that once some American girls had started dancing in the street during Dergah Puja, and a crowd of five hundred men gathered within five minutes. But we were within the school walls, and that girl had been dancing alone earlier. Someone said, “Come on! If we all do it, it won’t be that bad!” We danced on the stage in the hot sun.

The boys had moves, and we tried to copy them, bouncing our knees, raising our arms and spreading our fingers. I tried to bend back and touch the ground like one of the boys did, but I tripped up, and one boy said “Is good! You try, you try!” Every time we tried to leave the stage, they said “five more minutes!” until finally Sister Shoba lead us back to the chairs. She looked a little embarrassed for us. “If you had not stopped them, it would have gone on all evening,” she said.

She told us that all the performance had been planned for us that day. I wondered what they’d have looked like if they’d had time to practice.

Sister Shoba and the teachers answered our questions about the school and showed us around. The school was founded in 1991 and now has five hundred students. A group of mediation teacher at the Thai temple had wanted to start a school, and they asked our abbot, the abbot of the Burmese Vihar, to run it because he has helped build and run so many monasteries. Most of the students are younger because a lot of them drop out early for marriage or other reasons. All the students attend for free, but admission is somewhat competitive. The poorest students are given preference, but some higher-caste students are accepted so that the classes can mix. Once the students are in school, the teachers to their best to keep caste hidden. All the students wear uniforms, but on the first day many come very dirty. When that happens, all the dirty students are forcefully sent home to take a bath. “Very soon they begin to come very smartly on their own,” Sister Shoba said. The school tries to teach religious acceptance as well. The students say all the different prayers: Hindu, Muslim, Christian and Buddhist. Of the 500 students, most are Hindu or Muslim. The are five Christians and no Buddhists. Sister Shoba told us that she was Catholic.

“‘Tis a very rare thing, for a Catholic nun to run a school like this,” she said.

Inside the school, we saw tiny classrooms painted blue. We saw the three or four computers that all the students use to learn. The ceiling fans had “World Peace” written in Hindi on each blade. From the upper stories and the roof, we got a good view of nearby rice fields and the Chinese and Tibetan temples.

Sister Shoba said that the school’s main problems are financial. Someone asked if they got money from the government.

“No. And we wouldn’t want because then we have to follow government rules.”

Thursday, September 30, 2010

Bill Gross says don't expect double-digit returns anymore

He could very well be right. Part of returns come from inflation, which is currently running at an annual pace of 1.2 percent. If "normal" inflation is 3 percent, a 10 percent return in normal times is equivalent in real terms to 8 percent now. There is nothing necessarily wrong with that.

Tuesday, September 28, 2010

A modest step toward untangling housing markets

One of the impediments to housing transactions is appraisals. If appraisals (which are backward looking) don't support the offer price of a house, the financing for the house can disappear.

For low down payment deals, this is frustrating, but appropriate. But for deals involving a minimum of 20 percent down, it is hard to see how appraisers have a better sense of value than the potential buyer who is actually putting a lot of money at risk. It may make sense to allow buyers who put 20 percent down, and whose source of funds is well documented, to get a loan even if the appraisal comes in a little low.

Sunday, September 26, 2010

At what point will short sales become meaningful to restarting the housing market?

The Washington Post today forecasts 400,000 short sales this year. Lawrence Yun says there will be 2.5 million foreclosures in 2010. So while short sales have have increased substantially, they will still be only about 1/6 the number of foreclosures.

Tuesday, September 21, 2010

Don't get too excited

Nick Timiraos retweets Brad Hunter: Census numbers: Single family starts up 4.3% (+/- 12.4%) Plus or minus 12.4%!! It's in the fine print of their release!

I actually try my best not too make too big a deal out of any monthly number.

Sunday, September 19, 2010

To my macroeconomist friends: if you are going to do urban economics, please read the urban economics literature first.

I saw a paper from a famous macroeconomist a week or so ago that proposed that cities with high incomes relative to house prices produce more utility than those cities with low incomes realtive to house prices. Using this metric, he concluded that Flint was among the five highest utility cities in the US. This might have been a clue that there was something wrong with his utility measure.

The systems of cities literature (see Jan Brueckner's chapter in the Handbook of Urban Economics) and the quality of life literature (see Stuart Gabriel Joe Mattey & William Wascher's RSUE paper) shows that in a country with mobility, utility tends to get equalized across cities, and so that places with high house prices relative to income have more non-housing amenities than places with lower house prices. I can testify to the reasonableness of of this, as while Los Angeles is expensive (as well as congested), I do not find myself tempted to move anywhere else, suggesting that I, at least, derive a great deal of utility from living here (I recognize that lots of people are not so enamored of LA, but enough of us are to keep the price of housing high relative to other places). Other places like LA include New York, London, Paris, Singapore, Tokyo, Hong Kong, Sydney, etc.

This produces an efficient outcome, for if Los Angeles were less expensive, it would be even more congested. On the other hand, St. Louis' cheap house prices should eventually attract people back to it. But it also produces an unfair outcome, because it is very difficult for low income people in Los Angeles to find reasonably priced housing in reasonable locations. Perhaps the goal of housing policy should be to allow everyone to be able to choose the city in which to live, while at the same time distorting the relative prices of cities as little as possible. I am not sure how one does both.

Wednesday, September 15, 2010

While Arrow showed the impossibility of a well defined ordering of social preferences...

...we tend to act as if there is one anyway. That is, we place a lot of focus on GDP per capita when evaluating economic success. By this measure, the US is, of course, successful. By a slightly different measure from the OECD (go to page 37), average disposable income per household, the US ranks second after Luxembourg among the nations measured. Luxembourg has about the same population of Long Beach, so it is hard to worry too much about it.

But a social welfare function that looks at the lowest decile of income is just as legitimate (or perhaps I should say, illegitimate). By this measure, the US ranks 20th among countries measured, which places it toward the bottom of the OECD pack, with levels similar to Greece and Italy.

On the other hand, the top 40 percent of American household are better off than their counterparts in all other countries (with the exception of Luxembourg), reflecting a great deal of affluence across a large number of people. So where to pick? As Arrow would say, that is really impossible.

Saturday, September 11, 2010

When assumptions drive the result

I have spent the past few days at the Wisconsin-St Louis Fed conference on Housing, Urban, Labor and Macroeconomics; it is a third in a series that Morris Davis had organized, and the papers were thought-provoking and well done.

The macro paper, however, was about whether government can effectively counteract negative shocks to one sector of the economy. To the standard macro model it added a friction where workers had to retrain in the event of a shock to one sector of the economy so as to be able to work in another sector. This is clever and important.

But while the model allowed for frictions, it failed to allow for involuntary unemployment, and so it found that government interventions were ineffective. Well, duh...

Wednesday, September 08, 2010

Is it housing or is it Boston?

David Leonhardt's excellent piece on house prices in the New York Times this morning asks a fundamental question about how to think about the future of house prices. If houses are a staple, they are currently overvalued by historical standards; if they are a luxury good, they are not.

Mr. Leonhardt's definition of a luxury good is one with an income elasticity equal to one (i.e., a good where the share of income spent on the good remains constant), whereas technically speaking, luxury goods have income elasticities greater than one (think nice vacations). But the point is still a good one--the income elasticity of demand for housing should tell us a lot about where house prices "should be" right now.

National house prices did follow income closely between 1970 and 2000, while according to Robert Shiller, they grew only by the rate of inflation before that. I wonder if the reason for the change is not that people wanted to spend a constant fraction of their income on housing, but rather that they wanted to spend a constant (or even increasing) fraction of their income on certain cities, such as Boston, New York, San Francisco and Los Angeles. These are all high amenity places, chock full of luxury goods, that have inelastic housing supply. It is possible that housing in, say, Wichita (sorry to the Kansans out there) is a staple, while Santa Barbara is a luxury.

Monday, September 06, 2010

LA commutes? Not so bad.

The average one-way LA commute is 29 minutes. This compares with 45 minutes for the UK (the whole country, not just urban areas) and 38 minutes for the EU. A variety of sources suggests that the median commuting time in Japan is greater than 30 minutes and the average is longer (because of skewed data).

European cities are great for vacations, and wealthy people in such cities can live in places that allow them to walk to work. But for average people, LA is a easier place to get around.

Ryan Avent of The Economist gets it right (h/t to Mark Thoma)

He writes:

"...it's simply not true that the administration has rolled out every programme it can think of. Economists with which administration officials are very familiar have proposed measures to deal with the real problem in housing markets: negative equity. Promising policies like mortgage cramdowns and own-to-rent programmes have yet to get a serious look from Washington leaders. But ultimately, a real fix for housing markets must address underwater mortgages. Absent some attempt to deal with negative equity, a rush of buyers into the market will accomplish little; the problem is that underwater homeowners can't afford to sell at prevailing prices. Driving those prices lower won't change that fact.

The truth is that the trouble in housing is not, for the most part, a demand-side issue. The problem is the millions of homeowners stuck in houses they can't afford to sell. These households represent a significant shadow supply of foreclosures-in-waiting. I agree that it would be silly for the administration to try to support housing prices by offering more goodies to potential homebuyers. But it doesn't follow that letting prices go their own way will magically get housing markets moving again."

John Quigley, Alan Blinder (and I for that matter) have been advocating something like a Home Owners Loan Corporation, and/or a debt equity swap for underwater mortgages for some time. We also need to deal with second liens--investors in such liens are holding up renegotiated mortgages because they will get wiped out--which is of course what is supposed to happen when one interest is subordinate to another.

(Thanks to Jim for filling me in on who RA is).

Sunday, September 05, 2010

A downpayment factoid

Canada allows 95 percent LTV loans. Borrowers must get mortgage insurance, either from the government or the private sector, if the LTV exceeds 80 percent. Yet 90 day delinquencies there remain under 50 basis points. All home lenders in Canada are subject to strong regulatory oversight.

Friday, September 03, 2010

My favorite Art Goldberger quote

I saw a paper today on heritability and savings. It made me think of my econometrics teacher, Art Goldberger, who once wrote:

Professor Hans Eysenck was so moved by the twin study that he immedi- ately announced to Hodgkinson that it "really tells the [Royal] Commis- sion [on the Distribution of Income and Wealth] that they might as well pack up" (The Times, 13 May 1977). (A powerful intellect was at work. In the same vein, if it were shown that a large proportion of the variance in eyesight were due to genetic causes, then the Royal Commission on the Distribution of Eyeglasses might as well pack up. And if it were shown that most of the variation in rainfall is due to natural causes, then the Royal Commission on the Distribution of Umbrellas could pack up too.)

From "Heritability," Economica, 1979, 46, 327-47.

Thursday, September 02, 2010

Do low rates make house prices more volatile?

Over at the FT blog, Cardiff Garcia has a nice summary of three papers that attempt to explain the run-up in house prices before 2007. It particularly approves of the work of my friend and co-author Susan Wachter and Andrew Levitan, who argue that a supply-side credit bubble produced the housing bubble.

As I read the piece, though, I couldn't help but think that while it is unlikely that low interest rates would explain prices, they might explain volatility. When nominal interest rates are low, a small change in price expectations can lead to a large change in prices.

Consider the Gordon Growth model, where Value = dividend/(i-g), where in this case the dividend is the value of living in a house, i is the interest rate and g is the expected growth rate of the dividend. Let everything be real (i.e., not nominal) Consider two worlds: 2 percent real interest rate world and a 4 percent world. Now let expectations about growth vary from negative one percent to positive one percent. In the two percent world, the upside scenario produces three times the value of the downside scenario. In the four percent world, the upside produces 67 percent greater value than the downside. Hence small changes in expectations have a much larger impact in a low interest rate environment than a high interest rate environment. It may be hard to pick this up because expectations are so difficult to measure.

Just a thought.

Tuesday, August 31, 2010

The wonders of academia

I became a full professor at the University of Wisconsin-Madison in 2001. Among the responsibilities of full professors are (1) to evaluate whether professor at schools other than ours merit promotion and (2) to chair and serve on promotion committees at our own schools.

So far as I can tell, senior faculty take these responsibilities very seriously. The strange part is that we take promotions of people at other schools very seriously, even though we compete with those very schools. I suppose one could make an argument that we at USC should try to blow up the cases of those who we deem to be good at other schools in California, while also waxing enthusiastic about weaker faculty at these schools. It is as if Honda were telling Toyota who to promote, and vice versa.

In the end, though, faculty at one school tend to recommend that faculty they deem meritorious at another receive promotion. While the process is certainly less than perfect, the good faith that most faculty show in these affairs helps explain why the US still has the best research universities in the world.

Sunday, August 29, 2010

Did Californians break their contract?

Mark Thoma, whom I admire, approvingly posts Michael O'Hare's letter to his students. Professor O'Hare says something that really bothers me:

...for a variety of reasons, California voters realized that while they had done very well from the existing contract, they could do even better by walking away from their obligations and spending what they had inherited on themselves. “My kids are finished with school; why should I pay taxes for someone else’s? Posterity never did anything for me!”

As Professor O'Hare correctly notes in the header to his blog, "everyone is entitled to his own opinion, but not his own facts."

So before we accuse middle-aged Californians of being greedy, we should consider four things. First, California ranks 4th in state and local per capita spending in the country (and number one is Alaska, where the tax price of government service is essentially zero). Second, about 2/3 of California bond referenda that go to the public receive the 2/3 super-majority necessary to get passed. Third, we in Los Angeles County voted two years ago, in the middle of a recession, to tax ourselves to pay for transportation infrastructure. Finally, we absorb more people from the rest of the world relative to our population than any other state. These facts are more consistent with generosity than greed.

I understand Professor O'Hare's frustration with California's state budget process and with the threats against the wonderful UC and Cal State systems. Those who know me know that I enthusiastically support all kinds of public spending. But Professor O'Hare's rhetoric could well alienate many whom he wants on his side, and may actually give aid and comfort to the Sarah Palins and Glenn Becks of the world.

Friday, August 27, 2010

Maybe we are more like Homer Simpson than Spock

I saw Juan Carrillo of the USC economics department present a very nice paper testing auction theory using experimental data. The only problem was that the people in the experiment were Cal Tech students, who are not exactly representative. But even Cal Tech students, while likely more rational than the general population, and who certainly understand experiments better than the general population, are still far less than perfectly rational.

Thursday, August 26, 2010

What is the correct downpayment?

If required down-payments are too low, we get the nonsense of the past several years. I am reasonably sure zero is too low. If required down-payments are too high, we, among other things, perpetuate wealth disparities (i.e., the only people who get credit are those that don't need it). I am reasonably sure that 25 percent is too high.

What is both socially optimal and just? We need to try to figure this out, but it would involve knowing the correct social loss function and then minimizing it. Social welfare functions are very, very tricky businesses.

Tuesday, August 24, 2010

In praise of Lawrence Yun

As Robbie Whelen notes in the Wall Street Journal, it could not have been fun to be Lawrence Yun, the National Association of Realtors chief economist, today. As Whelen notes, he must "toe the line between housing industry economist and housing industry motivational speaker."

I think Lawrence does this well--he is clearly on the side of the people who pay him, but he also takes his positions honestly. I assume that he had something to do with NAR's decision not to advocate for an extension of the home buying tax credit. More important, he is in charge of the data that NAR puts out, and bad days like today essentially prove that the data are credible (full disclosure: I, along with Orawin Velz and Kevin Thorpe, helped design the methods by which the Existing Home Sales data are produced, but I have nothing to do with the monthly estimates that NAR puts out). I am guessing that one or two members of NAR wish he would fudge the data, but he does not.

No more goosing with tax credits please.

The July Existing Home Sales number of 3.8 million units was abysmal--it was 1980s bad. I am guessing that a lot is it is that July gave back the tax credit driven boost of spring. If we look at average sales for the year, it is 5.1 million, which is pretty much normal. March, April, May and June were above normal, but all of that "strength" was given back in July. Credits just pull sales forward--they don't change the underlying dynamic, and they add to the deficit.

Sunday, August 22, 2010

Is housing the best way for low-income people to build wealth?

I was thrilled to be invited to the Future of Housing Finance conference held at the Treasury Department and co-sponsored by HUD this week. It was particularly nice to be seated next to Self-Help's Martin Eakes, whom I have admired for some time. Like Elizabeth Warren, Eakes long ago had insights into sub-prime lending that I wish more of us had taken seriously.

At the conference, Martin worried about a conversation that emphasized the need for robust underwriting standards for the mortgage market going forward. The three most important standards are loan-to-value ratio, payment-to-income ratio, and credit history. As Martin pointed out, African-Americans have less wealth available for down-payment than others (even after controlling for income), and have lower FICO scores than others, and therefore will be denied access to credit at a greater rate than others if underwriting standards are tough and uniform. Because much of the reason that African-Americans lack wealth is because they have been systematically stripped of wealth for many generations, policies that reduce access to credit disproportionately for African-Americans violate fairness.

The events of the past six or seven years show that loose underwriting does nobody any favors, either. Foreclosures are terrible things for the families who experience them and for the communities that have large numbers of them. The whole point of underwriting is to prevent default and foreclosure, and the unpleasant fact is that downpayment and FICO are predictors of likelihood of default.

In the era where almost all mortgages were self-amortizing, housing allowed families to build wealth because mortgages were a form of forced saving. Those who got a 20 year mortgage in 1960 owned their house free and clear in 1980; households gained wealth not because housing was such a great investment, but because they built equity, month after month. Housing was a particularly attractive way for those of modest means to save, because they could live in the very piggy bank they were building. In principle, however, these households could have rented and taken the difference between a mortgage payment and a rental payment and put it in another investment (a small business or the stock market). But we know that in the absence of nudges, people tend to save less.

Perhaps, then, the government could come at the savings issue more directly by giving low-income people a nudge toward saving. Suppose it developed a 401(k) type plan that matched the savings of those with below-median incomes at 2 to 1. This would encourage savings that then could be used for a down payment or a host of other investments (say a Vanguard index fund). This would cost taxpayers money, but perhaps less than mortgage programs built on thin underwriting standards. At the same time, getting people into the habit of savings could produce other social benefits as well. I am not sure such a plan is practical, but I think we do need to think about how we can help people who have been denied wealth for generations how to start accumulating assets without relying entirely on the housing finance system to do it.

Friday, August 20, 2010

Rankings

The US News rankings of colleges came out the other day, and I will confess that I enjoyed the fact that we at USC moved slightly ahead of UCLA and were just one spot behind Berkeley. We also tied with Carnegie-Mellon.

I also enjoyed this piece by Colin Driver in the Atlantic on what it is like to run a place (Reed College) that refused to participate in the rankings: he finds it liberating, particularly after being the law school dean at Penn, where he had to fill out a survey rating every other law school in the country.

I have reservations enough about the US News college rankings, but the professional schools rankings are something else altogether--they are based heavily on reputation. When I was Associate Dean for Graduate Programs at GW, I had to fill out a survey rating every MBA program in the country. Of course, I was completely clueless about the vast majority of them (University of Utah? Could be great, could be awful, I just don't know). More important, I think it is hard to really know about a program unless you have worked in it for awhile. I do think I understand the strengths and weaknesses of Wisconsin, GW and USC, but that is about it. I probably can tell you whether a place is strong at research in my fields of interest, but that is about it.

Bill Gross' big idea

At Tuesday's conference on the Future of Housing Finance, Bill Gross suggested that anyone who was current on a Fannie/Freddie loan should automatically be refinanced to the current mortgage interest rate of about 4.5 percent. This should happen instantaneously, without underwriting.

I am trying to see the downside of this. It reduces the probability of default, because it reduces the present value of the loan balance and payments. It only rewards those who pay their mortgages on time. And as Bill Gross pointed out, it would amount to an enormous stimulus (what he didn't point out is that the stimulus would be at least partly funded by foreign holders of MBS).

Monday, August 16, 2010

Where should transit $$$ be spent?

I flew to Washington today for the big conference on the future of housing finance in the US. When I arrived at Dulles, I checked to see how long I would have to wait to catch the Washington Flyer bus to the Falls Church West Metro stop. It was five minutes, so I took it. It costs $10, and takes about 15-20 minutes from Dulles to the Metro.

Once I got to West Falls Church, I waited less than two minutes to catch an Orange Line train into town, so all seemed to be well, until not just one, but two trains broke down in front of us. It took about 45 minutes to get from Falls Church West to Foggy Bottom, a distance of perhaps eight miles. At that point, I left the Metro and caught a cab to my hotel in Dupont Circle.

Metro needs to spend money on maintaining and replacing cars and tracks in its current system; instead it is spending money on extending service to Dulles. There is a dedicated roadway to Dulles that makes bus travel fast and easy. The only problem is that the buses depart every 30 minutes; if they left the airport every ten minutes, they would be an attractive method of connecting to the rail system; such service would also be far less expensive than building heavy rail out to the airport.

The savings, then, could go to keeping curing the deferred maintenance of the current system. Alas, politicians don't seem to think that maintenance wins votes.

Saturday, August 14, 2010

What is a renter?

Richard Florida, among others, has suggested that the United States overindulges in homeownership, and that rental housing gives flexibility to people such that they become more creative. I have no quarrel with the idea that homeownership has been oversold. A paper I wrote with Shelley White that showed that owning could be good for children has gotten cited a lot; a paper I wrote with Dean Gatzlaff and David Ling (that I thought was just as good as the paper with Shelley) that suggests owners maintain their homes no better than landlords has barely gotten cited at all.

But a lot of the story about why renting is great involves New York City. There can be no doubt that New York is an innovative and creative place, and that it has a lot of renters by national standards. But about 2/3rds of rental units in New York City are rent controlled or rent stabilized. If one occupies a rent controlled or stabilized apartment, he gets a lot of the benefits of owner-occupancy: reduced housing cost risks, and security of tenure. Renters in New York share far more of the bundle of rights than renters in most parts of the country; they are almost like owners expect for the possibility of capital appreciation. San Francisco, San Jose and Los Angeles, three other cities one might count as innovative, also have some form of rent control (what's more, property tax law in California encourages owners to move less than they otherwise would).

The point is that the owner-renter dichotomy is really a false one, as there are shades of tenure in between. These shades might matter a lot.

Thursday, August 12, 2010

Silliness

I keep running across pieces saying that urban farming can "save" Detroit. Agriculture makes up 1.3 percent of GDP for the United States, and there is a reason why it doesn't take place in cities--it is a low intensity land use. If Detroit really reverts to farming, it will only show that its economy really is gone forever.

Tuesday, August 10, 2010

One reason why Steven Slater might have lost it

I was listening to the inimitable Larry Mantle on KPCC this morning. The topic was spectacular job-quitting moments, and was, of course, inspired by Steve Slater's colorful departure from a jetBlue flight.

Because I fly a fair amount, I chat with flight attendants from time-to-time, and I have a few flight attendant friends who I met through other friends. They have been getting hammered: their wages, which were low before, are even lower, and many of the benefits they were counting on, such as pensions, have been severely reduced. At the same time, airplanes are getting more full, which means that the probability of encountering a rude passenger has gone up. It is no wonder people in the business feel more stress.

But it is not just flight attendants: it is workers in general. No matter how one looks at it, workers' share of the economic pie has been shrinking. The graph below is the ratio of total compensation to national income (data is from the BEA):
 
Note that the ratio peaked in 1980, and has been on a downward trend since.  Even more pronounced is the downward trend in the wage to national income ratio:


For those jobs (such as flight attendant) where benefits have gotten worse over time, the wage-to-national income data may be more relevant. Note that in 2006 this ratio fell to its lowest level in the post-World War II era.

Friday, August 06, 2010

Two stories in this morning's papers and the future of house prices

Firserve says that house prices will not regain their previous peaks in the sand state until 2025, and it will be even longer in places like Stockton.

This could well be right, except that I infer that Fiserv is looking at nominal house prices, whose dynamics are driven in part by the underlying general price level. As the New York Times notes this morning, Jan Hatzius predicts falling general price levels; Richard Berner says they will rise--if Hatzius is correct, it will of course take longer for house prices to return to the past peak; if Berner is right, it will take less time.

Thursday, August 05, 2010

Pithiness from Chicago

Diane Swonk is good at summarizing:

Moreover, government interventions (most notably regulation and austerity programs) are more likely to suppress growth than promote financial stability, which means we have learned very little from the crisis itself. The G-20 has been particularly bad at fostering coordination across country borders now that the crisis has passed. Financial reforms, in particular, are being implemented on a piecemeal basis, which could encourage--rather than discourage--the kind of regulatory arbitrage that got us into this mess in the first place.

The last point is important. While we still don't know the most important source of the crisis, regulatory arbitrage between shadow banks and regulated banks was almost surely a major contributor.

David Oser's take on Fannie and Freddie

The opening paragraph and closing paragraphs of his stimulating piece:

Some mistakes are so egregious and yet so uncorrectable that no one is willing to admit them. On Sunday September 7, 2008, US Treasury Secretary, Henry M. Paulson, made just such a mistake. He ordered Fannie Mae and Freddie Mac placed into “conservatorship,” an ambiguous category of quasi-receivership that still defies precise definition. To see why Paulson’ decision was so unwise, we’ll start by deconstructing a financial instrument that most people assume they understand perfectly well: the 30-year home mortgage....

....Here’s the bottom line. Before September 7, 2008, we had a mortgage system that, while rickety and obscured by smoke and mirrors, worked. It worked not because of an effective business model but because everybody—investors, lenders, and borrowers—realized it was in their best interest for it to work. Then Henry Paulson said, “Look, the emperor has no clothes,” as if that were news instead of common knowledge. Paulson chose conservatorship for Fannie and Freddie because it meant the Treasury only owned 79.9% of the two companies. One tenth more and their assets and liabilities would have gone into the federal balance sheet. That would have meant the federal government was explicitly guaranteeing all $5 trillion of Fannie and Freddie’s securitized mortgages and other debt. And that would have meant that the federal government was guaranteeing both sides of the consumer’s balance sheet: her bank accounts through FDIC insurance and now her mortgage.

If we were really Big Boys, we’d say, “Sorry. We messed up. We’re going to try to put it back the way it was.” But we aren’t that big and, as someone said to me recently, “Fannie and Freddie have become the third rail of American politics.” Instead, we’re going to let Fannie and Freddie totter along. In the words of Wall Street Journal editorialist Brian M. Carney, Fannie and Freddie are “money-losing zombie financial companies in the bosom of the federal government.” Maybe that criticism would be fair if Carney had a solution, but he doesn’t and neither does any one else. I don’t know that there is a solution. Fannie Mae, the older of the two companies, was created during the Depression when the typical mortgage had a five-year term with all the principal due at the end. Maybe that’s what we’ll go back to, so that only those who don’t really need a mortgage can get one.


I need to think about this a little. One thing, though, is that the Home Owners Loan Corporation and then Fannie Mae were the entities (along with FHA) that gave us the long-term, fixed rate mortgage. The HOLC mortgages generally had 15 years terms.

Monday, August 02, 2010

Add Metros to the Chinese List

From Planetizan:

With 420km of network, Shanghai's metro overtook the London Underground, which has a total of 402km. But the rate of expansion is more impressive: the first line was constructed in only 1995 and it is still expanding.

By 2020 Shanghai, "intends to have added over 350km in new lines and extensions, almost doubling its network length."

However, "there is no suburban commuter rail system in Shanghai that compares with those in cities like London, Paris and Tokyo, where the railway network is essentially operated as a secondary rapid transit system with longer station intervals than the subway, generally with an interchangeable fare system."

Chinese cities have 8-10 times the density of our densest cities, and so metros make lots of economic sense there.

Saturday, July 31, 2010

Chinese Highways

China now has about 65,000 kilometers of freeway criss-crossing the country. In 1989, the number of kilometers was zero. To get a sense of the magnitude of this achievement, the Interstate Highway system is about 75,000 kilometers long and took about 40 years to complete.

This does not mean the US should go on a freeway building spree (the marginal productivity of length almost surely decreases in length); it is just one measure of explaining how China has developed so rapidly.

Friday, July 30, 2010

There they go again

I enjoy David Brooks. From everything I can tell, he is smart and has a good heart. I would guess he is a terrific dinner companion. So I was disappointed when I read in his column this morning:

What we have is not just a cycle but a condition. We could look back on the period between 1980 and 2006 as the long boom ...

Sorry, David, but 1980 to 2006 was not a long boom. Consult the National Income and Product Accounts tables, and you will find that real GDP over that time grew about 3.1 percent per year. In the "awful" Nixon-Ford-Carter 1970s, growth was 3.2 percent per year; in the 60s 4.2 percent; in the 50s 3.5 percent, and in the 40s 5.6 percent.

It is not that 1980-2006 was bad, just hardly a boom relative to the previous 40 years.

Thursday, July 29, 2010

Steve Malpezzi is not happy

He blogs:

When I first heard of HAUP, I was excited, but my excitement quickly turned to disappointment. Among other problems, it requires that unemployed homeowners go through a fairly bureaucratic procedure to apply for what is (more or less) three months forbearance. And that' s merely the application; forbearance may or may not be granted for the 3 months. Remember, at the present time, the AVERAGE duration of unemployment is 9 months and rising.

(The fine print says you can extend beyond 3 months, but it's not clear that will happen, and will certainly not be clear to potential applicants).

The website's FAQs does not even tell people if the differences between the original payments and the reduced payments, are forgiven, or wrapped into the loan. (When I inquired of the experts in Washington, it turns out part of the loan is forborne, adding to the loan amount, but it’s amazing that they ask people to apply without clearly explaining such a key element of the program!)

What if your unemployment lasts more than three months (which is true for most unemployed today?) After two months you are given an application for HAMP, the dog that won't hunt. As far as I can tell, most unemployed will still not qualify for HAMP after they fill out this application.

There are other details that limit the program’s scope, and hence its effectiveness at halting the skid in housing prices. Homeowners can't get relief on the second liens. And if I read it right, HAUP does nothing for the unemployed not receiving unemployment insurance.

My bottom line: Treasury is still spitting on the fire and leaving the hoses coiled up.

Wednesday, July 28, 2010

David Leonhardt writes that Kindergarten matters

From the encouraging article:

On Tuesday, Mr. Chetty presented the findings — not yet peer-reviewed — at an academic conference in Cambridge, Mass. They’re fairly explosive.

Just as in other studies, the Tennessee experiment found that some teachers were able to help students learn vastly more than other teachers. And just as in other studies, the effect largely disappeared by junior high, based on test scores. Yet when Mr. Chetty and his colleagues took another look at the students in adulthood, they discovered that the legacy of kindergarten had re-emerged.

Students who had learned much more in kindergarten were more likely to go to college than students with otherwise similar backgrounds. Students who learned more were also less likely to become single parents. As adults, they were more likely to be saving for retirement. Perhaps most striking, they were earning more.

All else equal, they were making about an extra $100 a year at age 27 for every percentile they had moved up the test-score distribution over the course of kindergarten. A student who went from average to the 60th percentile — a typical jump for a 5-year-old with a good teacher — could expect to make about $1,000 more a year at age 27 than a student who remained at the average. Over time, the effect seems to grow, too.

The economists don’t pretend to know the exact causes. But it’s not hard to come up with plausible guesses. Good early education can impart skills that last a lifetime — patience, discipline, manners, perseverance. The tests that 5-year-olds take may pick up these skills, even if later multiple-choice tests do not.

Two really important points here: (1) early education does seem to matter; (2) the multiple choice tests we give older students may be deeply flawed. This is particularly problematic if these later tests are the foundation for evaluating our educational system.

The Hidden Leverage of Mortgage Securitization

Ed Glaeser has a nice piece about the debate over whether securitization should get the blame for the subprime mess. But it doesn't address one of the problems created by securitization: hidden leverage.

When banks (commercial and investment) sold off mortgage backed securities, they got them off their balance sheets, and so there was a pretense that they were no longer liabilities. But in order to sell the MBS, the lenders had to offer repurchase agreements, which said that if there was something materially wrong with the loan underwriting, the investor could return the mortgage backed security to the lender at par. Lenders also often kept residual positions of mortgage backed securities, meaning that to reassure investors, the lenders (i.e., the sellers of the securities) would take first loss positions.

Both repurchase agreements and residuals effectively increased the leverage taken on by lenders. Let me illustrate: suppose a lender has an whole asset and capital of ten percent, and the asset loses one percent of its value. The lender takes a ten percent hit against capital, because it is levered at 10 to one. But now suppose it takes a first loss position of ten percent on residuals, and the mortgage underlying the residuals lose one percent of value. The residual loses ten percent of its value, which means it wipes out the capital that is implicitly backing it. The combination of ten percent capital and a ten percent first loss position implies actual leverage of [updated: 100 to 1].

Ironically, the fact that financial institutions ate some of their own cooking--something that should have mitigated moral hazard--made them more vulnerable.

Friday, July 23, 2010

Raphael Bostic on housing tenure policy

From Newsweek:


Another senior HUD official was more direct in an interview with the Washington Post recently: "In previous eras, we haven't seen people question whether homeownership was the right decision. It was just assumed that's where you want to go. You're not going to hear us say that."

That official was Raphael Bostic, a leading scholar on home finance [rg note: and USC professor] and key policy adviser. An NPR report on Thursday morning said senior officials have acknowledged that their HAMP plan was largely a failure, and were leaning toward policy goals that promoted renting rather than buying. As a result, the report said, Fannie and Freddie might be entirely liquidated.

Thursday, July 22, 2010

No people with memory loss in my back yard

In the midst of doing research on how NIMBYs fight facility for housing the elderly, I came across this story from last March in the Minneapolis Star Tribune:

When a released sex offender plans to move in next door, or a drug-treatment center is scoping sites for a new halfway house, a neighborhood's red flags invariably follow.

Now, the list of objectionable neighbors is growing.

In the face of overwhelming opposition from residents in an upscale community called Stonemill Farms in eastern Woodbury, plans for a 45-unit assisted-living facility for people with Alzheimer's disease and other forms of dementia have been put on hold.

The Alzheimer's facility is the latest in a growing list of projects across the metro that are meeting resistance from neighbors who perceive a threat to their communities or fear their property values will erode.

A decision on whether to recommend the Woodbury project for approval was to go before the city's Planning Commission on April 5, but the developer on Wednesday asked for more time to address issues, including concerns raised by neighbors, said Eric Searles, associate planner for Woodbury.

The move follows nearly a month of intensive protests and petitions by neighbors who mainly object to locating the facility in a failed retail site near a day care center and across the street from an elementary school. Many have also expressed a sense of betrayal that the original plans for the community never envisioned an assisted-living facility.

The facility would go into a dead retail center: turning vacant space into useful space usually improves neighborhoods. The idea that Alzheimer's patients pose a risk to children is beyond preposterous. I understand having land use controls so that property owners don't have to deal with genuine nuisances, such as oil refineries. But what kind of people seek to deny the infirm a decent place to live? One hopes that once these neighbors are stricken with Alzheimer's, they retain enough of their long term memory to remember how badly they behaved.

Tuesday, July 20, 2010

As I read the Washington Post "Top Secret America" series...

...I can't help but wonder how much deadweight loss this is all creating. The theatrics one encounters in airports also seems like it creates frictions that must have an impact on the economy--the ability to travel freely matters to economic productivity, and we travel less freely than we did ten years ago.

Fans of Ronald Reagan maintain that he got the Soviets to destroy themselves by making them spend so much on their defense (I think containment might have also had something to do with it). While as a fraction of GDP, our defense, security and intelligence spending is much smaller than the Soviet defense apparatus, the "invisible" impact of this stuff on the economy must be material. I some days wonder if we are doing exactly what Osama bin Laden wants us to do.

Saturday, July 17, 2010

How Economics is better than Nassim Taleb says it is

The Black Swan is a great book, and deserves the hype it has received. It also features lots of nasty comments about economics, most of which the profession deserves.

But economics training (or at least my Wisconsin economics training) teaches empirical skepticism (something Taleb advocates) all the time. We worry about mis-measurement of variables, omitted variables, selection, reverse causality, and distributions all the time. We think hard about things we don't observe--in my context, when I think about measuring house prices, I worry about the fact that we only observe houses that actually sell. We do non-parametric statistics, and we reject the assumption of normality on a regular basis.

As a result of all this, economics has actually helped us understand certain things better, at least within the realm of applied microeconomics. One a lighter note, let me state an untestable hypothesis--of all the "silent" music that has been written, none has been better than J.S. Bach's.

Friday, July 09, 2010

Yves Smith on the Default of the Rich

She writes about this morning's story in the New York Times:


Another message here is that high income borrowers aren’t taking the Freddie/Fannie/bank bluster about strategic defaults seriously. Recall that the latest threat was that they would pursue deficiency judgments, as in sue borrowers who defaulted where the proceeds from the sale of the home, net of expenses, did not cover the mortgage debt. Now in some states that is not permitted (purchase money mortgages in many states are non-recourse, but refis never are). But independent of that, it is expensive to pursue defaulting borrowers, and if the borrower really is broke (say he had medical emergency, a business failure, or a costly divorce) litigation is just a costly wild goose chase. The most obvious group to pursue, nevertheless, would be defaulted owners of big ticket homes in affluent areas. They clearly regard the odds of legal action as low.

She slips in an important sentence--that refinanced mortgages lose their non-recourse status. Refinancings swamped purchase money mortgages in 2004 and were a substantial share of the market in 2005-2006. It would be interesting to see an estimate of the share of mortgage debt outstanding in "non-recourse" states that actually now come with recourse--I would imagine it is well over 50 percent. One might think that "sophisticated" investors are more likely to refinance than the general public (I did a paper with Lacour-Little some time ago that suggested that this was true), and so that "strategic" default could be particularly costly for this group. Certainly, if I were a lender and observed a borrower with a $1 million plus loan with recourse, I would go after the borrower for a deficiency judgment.

There is a broader point here as well. I have been reading arguments that America got itself into trouble because it is too borrower friendly, and that countries that avoided trouble, such as Canada and Germany, did so because of recourse. But the fact is that for all intents and purposes, the US is a recourse country too.

Thursday, July 08, 2010

Two more thoughts about The Big Short

(1) One of Hayek's most compelling arguments for the virtues of markets over government is that markets (via prices) reflect the constantly shifting preferences of millions of agents, and as such are both efficient and democratic. But the market for Collateralized Debt Obligations and Credit Default Swaps did not reflect the preferences of millions--they reflected the views of a very small number of people, some of whom had enormous market power (for awhile, anyway). A takeaway from the book is how large institutions could rig prices of over-the-counter investments for long enough periods to do substantial damage.

(2) While I loved the book, and will indeed use it in class, it may suffer a bit from ex-post thinking. The heroes of the book, Michael Burry, Steve Eisman, Greg Lippman, bet early and often against subprime mortgages, and made lots of money as a result. Ex post, their bets seem obvious, and perhaps ex ante, they should have seemed obvious. My strong suspicion is that Burry--who went to the bother of actually reading and analyzing offering circulars--really did know that he had a positive NPV bet ex ante. And loan originators surely knew they were underwriting junk, because documentation was so week. But perhaps not even Burry knew how big his pay-off would actually be.

Friday, July 02, 2010

Steve Malpezzi's Reading for Life

It is on the Wisconsin Real Estate blog:

13. Ahamed, Liaquat. Lords of Finance: The Bankers Who Broke the World. Penguin Press, 2009.

12. Akerlof, George A. and Robert J. Shiller. Animal Spirits: How Human Psychology Drives the Economy, and Why It Matters for Global Capitalism. Princeton Unversity Press, 2009.

11. Bartik, Timothy J. Who Benefits from State and Local Economic Development Policies? Kalamazoo: W.E. Upjohn Institute for Employment Research, 1991.

10. Cronon, William. Nature's Metropolis: Chicago and the Great West. W.W. Norton, 1991.

9. Gomez-Ibanez, Jose A., William B. Tye and Clifford Winston (eds.). Essays in Transportation Economics and Policy: A Handbook in Honor of John R. Meyer. Brookings, 1999.

8. Green, Richard and Stephen Malpezzi, A Primer on U.S. Housing Markets and Policy. The Urban Institute Press for the American Real Estate and Urban Economics Association, 2003.

7. Hulme, Mike. Why We Disagree About Climate Change: Understanding Controversy, Inaction and Opportunity. Cambridge University Press, 2009.

6. Lewis, Michael. The Big Short: Inside the Doomsday Machine. W.W. Norton, 2010.

5. Reinhardt, Carmen M. and Kenneth S. Rogoff. This Time Is Different: A Panoramic View of Eight Centuries of Financial Crises. Princeton University Press, 2009.

4. Slemrod, Joel and Jon Bakija. Taxing Ourselves: A Citizen's Guide to the Debate over Taxes. MIT Press, 2008.

3. Tufte, Edward R. The Visual Display of Quantitative Information. Chesire, Connecticut: Graphics Press, 1983.

2. Wessel, David. In Fed We Trust: Ben Bernanke's War on the Great Panic. Crown Business, 2009.

1. http://wisconsinviewpoint.blogspot.com/

Ken Rogoff thinks the BP spill might produce a groundswell for a carbon tax...

...but Mark Thoma is not so sure [Rogoff's take is here].

I am actually more inclined to agree with Rogoff on this one. When environmental problems are easily visible, they seem to generate political consensus for action. The air quality in Los Angeles, which was obviously awful 30 years ago, is much better currently--the vast majority of days are quite clear now(although we still have the problem of invisible small particulates). The 1952 smog disaster led to major policy changes in the UK. The BP disaster could similarly mobilize policy.

Mark could still be right about this--I just hope he is not.

Thursday, July 01, 2010

I am putting Michael Lewis' The Big Short on my FBE 589 reading list for this fall

So many great lines. Perhaps my favorite (from pp 151-152):

The only interested parties missing from the conference were the ultimate borrowers, the American home buyers, but even they, in a way, were on hand, serving drinks, spinning wheels, and rolling dice. "Vegas was booming," said Danny. "The homeowners were at the f**king tables."

A couple of thoughts. First, I would bet (forgive the word) that gambling habits would be a good underwriting variable for predicting mortgage default. If lenders could know whether someone gambled more than one percent of their annual income in casinos, at the race track, or on lottery tickets, it might say something about propensity to repay a mortgage [full disclosure, I bet $18 once or twice a year at Santa Anita].

Second, I do remember being mystified at what happened to house prices on my street in Bethesda, Maryland. When my wife and I moved there in 2002, we thought it was awfully expensive, but decided that the schools and proximity to metro made it worth while. We swallowed hard and got a mortgage where our mortgage payments + property taxes were about 20 percent of our gross income. My wife was an attending physician at a large medical center, and I was a finance professor at George Washington.

By 2005 or so, the price of houses on our street had increased by about 2/3 (because all houses were 30s vintage colonials, every sale we observed was a good comp). The mysterious part was the buyers were young one-earner households. I wondered how on earth they were "affording" their houses. Now we know.

I don't blame Goldman Sachs for taking 100 cents on the dollar of its Credit Default Swaps from AIG....

....I blame the government for offering it. I understand that there was a need to keep Goldman stable, but jeez.