Monday, August 08, 2011

Paul Krugman lives his words

I hope that readers will forgive a personal anecdote.

Over the weekend, Paul Krugman wrote a blogpost entitled "Pulling Rank:"

I don’t have time right now to track down all the examples, but if you look at how many freshwater macroeconomists have responded to Keynesian arguments in this crisis, you find over and over again that they resort to assertions of privilege — basically, I am a famous macroeconomic expert and you aren’t — rather than really addressing the issues. And this is so ingrained a response, apparently, that they use it in situations where it’s truly ridiculous: Lucas accusing Christy Romer of not understanding basic macro, then demonstrating that he doesn’t understand Ricardian equivalence; Barro belittling the credentials of yours truly, just after forgetting that there was rationing and investment controls during World War II. 
Now for the anecdote part.  When I was a Ph.D. student in economics at Wisconsin, my advisor, Bob Baldwin, invited me to present a piece of our joint work at an NBER Conference called "Trade Policy Issues and Empirical Analysis."

I remember the night before the presentation--I had gotten to meet many of the people whose papers I had read in my graduate classes: Leamer, Feenstra, Rodrick...and Krugman.  It was at once a thrilling and scary experience, and when I went to bed that night, contemplating my audience for the next day, the fear took over from the thrill.  Let's just say that by the time morning rolled around, I am guessing my stomach had never been emptier.

I gave the presentation, and as best as I can tell, it went reasonably well.  I very much doubt he would remember it, but afterward Krugman, the young MIT full professor new trade theory rock star, came up to me, the nobody, Wisconsin graduate student,  to give me encouragement and advice on the paper.  He was very respectful--even collegial.  I will never forget it.

Robert Barro channels Marie Antoinette

In his Wall Street Journal column this morning, Barro argues that after a generation of policies that have increased income and wealth disparities, what we really need are policies that further increase income and wealth disparities.  For the sake of "liberals," however, he would countenance an exemption in his proposed VAT for food. I guess he is not willing to consider the importance of such an exemption to, say, people who don't have a lot of income.

Barro is among a class of economists to whom the median American is invisible.  They could all be played in the movies by Lionel Barrymore.


Saturday, August 06, 2011

Labor Statistics and Confidence Intervals

According to the BLS establishment survey, non-farm private and public employment rose by 117,000 jobs in July.   http://bls.gov/news.release/empsit.b.htm.  This number was better than the consensus forecast of growth of 85,000 jobs.  It led at least one business economist to say we have "avoided the precipice."

But can a monthly number really tell us that?  The technical notes for the employment report says the 90 percent confidence interval for the establishment survey is 100,000 jobs.  This means the estimate has a standard error of about 100,000/1.64 or about 61,000 jobs.  To the distance between the consensus forecast and the actual number reported is slightly more than 1/2 a standard deviation.  This means we can be only about 60 percent sure that the employment number was better than forecast, which is a little better than a coin flip.


Thursday, August 04, 2011

If that bridge, tunnel, runway, railway or road gets a 3 percent return

...it is a substantial positive NPV opportunity.  Who would have thought?

Monday, August 01, 2011

Yet another reason to never pay attention to interest rate forecasts

Yields--especially long-term yields--were supposed to rise on news of a debt ceiling deal; at least that is what I read would happen.

Bloomberg's end-of day yield curve, along with changes in yields for the day, is above.  Oh well.

This is not good for Los Angeles

Bloomberg reports:


Container-Ship Plunge Signals U.S. Slowdown.


San Pedro and Long Beach are the largest container ports in the US.

Sunday, July 31, 2011

Welcome to California, Elliot Hirshman

San Diego State University, a place I admire a lot, just hired Elliot Hirshman as its new president, at a controversial salary. I am not exactly sure what I believe about how much public university presidents and provosts should be paid, but I do know that Elliot was an excellent hire for SDSU, and therefore for California.

Elliot was Chief Research Officer at George Washington when I was there, and I served on a university committee that he chaired.  He was and am sure still is a good leader, good listener, and problem solver.  Research service for faculty at GW improved considerably during his tenure.  

If I am reading the deal correctly...

....this is not a compromise, this is a capitulation.  I am starting to think that Cornell West's characterization of Obama was correct.

Friday, July 29, 2011

Jenny Schuetz, Elizabeth Currid-Halkett and I have a new paper that has nothing to do with the debt crisis

It is here.

Abstract:     

The art market is famous – or notorious – for auctions at Sotheby’s and Christie’s at which works by well-known artists are sold for stratospheric prices. Researchers have argued that such prices are volatile and unpredictable based on economic fundamentals, implying that at least some segment of the art market behaves irrationally. In this paper, we examine whether the broader art market, composed mostly of small galleries, is more consistent with standard economic models. In particular, we ask whether the location patterns of art galleries exhibit behavior consistent with agglomeration economies, as would be predicted for retail firms selling highly differentiated and expensive products. Using a newly developed database, we find strong evidence of agglomeration economies among Manhattan art galleries from 1970-2003. Galleries locate in highly concentrated spatial clusters, and these clusters are more likely to occur in neighborhoods with affluent households and older, more expensive housing, consistent with locating near potential consumers. We find no evidence that galleries locate in cheap, “bohemian” neighborhoods. The highest quality tier of the art market, which has been most widely studied, contains a relatively small share of gallery establishments, although these “star” galleries have a longer average lifespan than non-star galleries. Locating near other galleries also increases the longevity of firms and establishments.

Thursday, July 28, 2011

Are we a 15 percent society or an 18 percent society?

Over the long term, federal revenues as a share of GDP have averaged around 18 19 percent over the past 20 years.  Currently, federal revenues as a share of GDP are about 15 percent.  Some of the difference arises from lower tax collections because of the recession, but most is the result of the Bush Tax cuts.  Obama cut taxes even more (yes, he has cut taxes--payroll tax reduction, housing tax credit, etc.).

The question is, do we want to be a 15 percent society?  I guess the Teapartiers would say yes.  But this would not just mean that we need to do things like slowly extend the retirement age and bend the cost curve on health care--it would mean that to reach long run sustainability, we would have to cut current benefit levels.

Even Paul Ryan's budget plan presumes revenues would increase to 18 19 percent of GDP--it just doesn't specify how to get there.  Personally, I think we can afford to spend even more on the sick and the elderly (and children), but we need to be willing to pay for it.  For the time being, I would be happy to return to the long-term revenue average.

If we follow the 15 percent path, we will be kicking grandmothers out of their wheelchairs.  We will be allowing children to be malnourished.  This is not demagoguery.  This is the cost of not being willing to tax ourselves at the level we have for many years taxed ourselves.

Tuesday, July 26, 2011

This is probably a crazy, stupid idea for getting around the debt ceiling, but...

...here goes anyway. 

Consider a 30-year Treasury Bond with a coupon of 4 percent and a par value of $100.  Treasuries pay every six months, so this produces 60 cash flows of $2 and then $100 at the end of the 30 years.

To make things easy, assume for a minute that that market is discounting 30-year bonds at 4 percent per year (or 2 percent per six months).  Suppose the US government offers investors a swap of 4 percent coupon bonds for 8 percent coupon bonds.  If we don't worry about duration issues for a moment, and use Excel notation (I don't know how to get Greek symbols in blogger), investors would be indifferent between:

PV(.02,60,2)+100/(1.02^60)

and

PV(.02,60,4X)+100X/(1.02^60).

X is the face value of the new bond, and comes out to about $58.99.  So the face value of the debt is reduced by 41 percent, while the value to investors remains constant.  Nothing of substance has changed (and actually duration risk is a little lower), but the balance sheet looks better.

I am sure I am missing some institutional thing here, or maybe my simple finance is off somehow, but still...


Don't lump everyone together, Professor Summers

In his response to Mark Thoma's "Great Divide," post, Larry Summers writes:
Second, as Keynes’ comments on the advantages of being conventionally wrong rather than unconventionally right illustrate, it is a serious mistake to overstate the insights possessed by practitioners in any field.  Anyone in mutual funds will tell you that active managers regularly outperform the market.  Only economic scientists realized they do not.  Contrary to the the implications of Thoma’s column, the best calls on the real estate bubble came from academics like Bob Shiller and Nouriel Roubini, not from any economists involved with the home building or realty industries.
While Summers' point about Bob Shiller and Nouriel Roubini is correct (and what was particularly impressive is that they explained the mechanisms that would create the destruction), he does not acknowledge that non-academic economics, such as Dean Baker and Chris Thornberg, also called the bubble.  On the other hand, lots of academic economists did not see the crisis coming (I certainly did not see the magnitude of it).


It is, moreover, not fair to lump Realtors and homebuilders together.  The Realtors' Chief Economist at the time (whose name I shall not mention) was ridiculous.  But while Dave Seiders, Chief Economist at the time with the National Association of Homebuilders, did not get it right, he did not do badly either.  I remember being impressed with NAHB at the time, because they were not being cheerleaders--they seemed to me to be playing things pretty straight down the middle.


Homer Simpson, Spock, Reaction Functions, and the Debt Ceiling

Imagine a game between Spock and Homer Simpson.  Spock's utility is maximized by saving the galaxy from destruction.  Homer Simpson's utility function is maximized by beer.  Spock gets some disutility from the amount of beer Homer Simpson drinks, because drinking makes Homer obnoxious, but it is less than the disutility he would get from the galaxy being destroyed.  Homer Simpson gets no disutility from the galaxy being destroyed, because he doesn't think it is possible.

Homer thus ties himself to the mast--he must get his beer no matter what--if he doesn't, he will allow the galaxy to be destroyed.  Homer therefore has a stronger negotiating position than Spock.  Similarly, people who think the earth is 4000 years old, that dinosaurs lived with humans, and don't believe there would be consequences to government default are in a stronger negotiating position.


The Mortgage Professor is Worried

Jack Guttentag writes:


...“If a default had the horrendous consequences you describe, and these induce Congress and the Administration to agree finally on an increase in the debt ceiling, how long would it take financial markets to return to normal?”
 Markets would never return to a state where US Government obligations are viewed as riskless. We will pay for this loss of grace forever.
 Investors in fixed-income securities are worse-case oriented, and make a major distinction between the impossible and the unlikely. The current rates that the Treasury must pay investors are based on the assumption that default is impossible. Once a default occurs, it will NEVER again be viewed as impossible. The additional cost of carrying debt on which default is possible will be paid forever....
Read the whole post.

Monday, July 25, 2011

Bad belt-tightening metaphors

A commonplace among politicians that drives me crazy is that "government must live within its means, just like families."

The problem is that families don't, at least within the meaning implied by the above statement.  Personal income in the United States is about $12.9 trillion.  Mortgage debt outstanding is about $10.5 trillion.  Consumer credit outstanding is about $2.4 trillion.  So the ratio of consumer debt relative to consumer income is similar to US government debt to GDP.

I am not saying we needn't worry about long term fiscal balance--we do.  As I have said before, we must, among other things, return tax revenues to at least their long-term mean as a share of GDP, and bend the cost-curve for health care--something that Obamacare actually tries to do. But bad metaphors that basically dishonestly flatter people are not helpful.


Sunday, July 24, 2011

Caltrans needs to fix this sign

Visitors to LA get misled by this old freeway sign on the Pasadena Freeway headed south:


The problem is that it is not an interchange with the 101 and the 5--it is just an interchange with the 101, which heads south a couple of miles to the 5.  People look for the 101 South and miss it, because it is nowhere to be found on signs.


Wednesday, July 20, 2011

Tastes in Tax Policy

I confess that I like the broad outlines of the Gang of Six plan.  I don't have a problem with people like me having to wait longer to retire, so long as people who do physical labor get held harmless. 

It occurs to me that I care about substantial progressivity at the bottom of the income distribution (and I am a big fan of the Earned Income Tax Credit).  To calculate progressivity, one needs to take into account ALL taxes, including FICA and state and local taxes.  I also need to think about Mark Thoma's point about the progeressivity of both taxes and benefits--maybe Europe is onto something in using regressive or proportional consumption taxes to finance a strongly progressive safety net.  I suppose the question is whether getting progressiveness out of taxes or spending produces less dead-weight loss.

But once income reaches a certain threshold ($100K per year?), proportional taxes are just fine with me.  A reasonablly flat rate structure with an earned income tax credit, few deductions, and a large exemption would do the trick.


Tuesday, July 19, 2011

Was it Murdoch who ditched the six columns?

This morning, James Taranto defends the Wall Street Journal against Joe Nocera's charges that the paper uses "Democrat" as an adjective.  Whatever.  But as I have been thinking about why I don't find the Journal as compelling as it used to be, it occurs to me that I loved its old lay-out: a lead news story in the left column and a deep feature story on the right.  Both stories would inevitably be rich with useful detail, and I think they made a lot of breakfast-time readers smarter.

I am not sure whether the front page was blown-up during the Murdoch era, but if it was, he has yet something else to answer for.

Monday, July 18, 2011

Lisa Schweitzer, again, writes something I wish I had written

She begins:

I think one of the reasons why there is a resistance to otherwise nice things like local foods and bicycling concerns the often terminally joyless way their advocates present the Great Social Good that The Better People Who Do These Things create, unlike you, you indolent, planet-killing dolt.


Read the whole thing.  

How does Michael Boskin do math?

He writes in the Wall Street Journal this morning:
The lower marginal tax rates in the 1980s led to the best quarter-century of economic performance in American history.
This didn't seem right to me, so I went to the National Income and Products Account web site.  For GDP growth after 1947 (the beginning of the quarterly NIPA data), the best 25 year period was between the first quarter of 1949 and the last quarter of 1973, when the economy grew by a multiple of 2.68.  This is well before Reagan took office.  The period of 25-year spells after Reagan took office is small, but the best period is the fourth quarter of 1982 until the third quarter of 2007, when the economy grew by a multiple of 2.26.

GDP growth likely overstates the benefit of the post Reagan era, because the benefits of the growth have been unevenly distributed.  If we look at median household income, it is really hard to figure out how to find a "best in history" 25 year period after Reagan.

Saturday, July 16, 2011

Why can't we have them?

In Asian and European hotels, there is a master switch near the front door of each guest room that is triggered by the insertion of a hotel key--when then key is not in, neither the lights nor air conditioning works.  It allows: (1) to always remember where one put his key and (2) to shut down lots of energy use on departure.

It is such a hassle free way to save energy, I am not sure why these devices aren't everywhere.

Good bye Wall Street Journal.

I have been reading the Wall Street Journal pretty much every day since I was in high school (yes, I was that nerdy--in that, and so many other ways, too).  I disagree with Joe Nocera that the paper has deteriorated badly--it still has many terrific reporters. The team that works on mortgage finance, including Nick Timiraos and Bob Haggerty, is better informed than their counterparts at other papers.

On the other hand, after more than 30 years, the Journal has ceased to be a daily must read for me now.  The Wall Street Journal once would have attacked the News Corporation scandal as fiercely as it attacked the Orange County bankruptcy story and the Enron and Worldcom stories. 

More important, the Murduchs have proven themselves even more eggregious than I expected.  Unlike last time, when David Wessel flattered me into renewing my subscription, I won't do so anymore.  The FT will have to go it alone.

Tuesday, July 12, 2011

One reason HAMP failed

A remarkable interagency group of economists wrote a paper that investigated the NPV test that is at the heart of HAMP: for a borrower to get a loan modification, the value of the modification must be on net greater than zero (or in the case of Fannie-Freddie loans, greater than -$5000).  In other words, the losses from expected default must be greater than the losses from modification.

An upshot of this rule is that borrowers who are deeply under water get no modifications--because the chance their loan will in the end cure is very small.  This means that borrowers in places that need HAMP most--Las Vegas, Phoenix, Florida, etc.--are least likely to get it, all else being equal.

It also underscores a basic point: in places where values have fallen by more than, say, 50 percent, anything less than principal balance relief just delays the inevitable.  When households in, say, Central California want to move or retire, their house sale will not be sufficient to cover their loan balance.   Even moving to make short sales easier would help.  Otherwise, it is hard to see how we can restart the market anytime soon.

Friday, July 08, 2011

Why is reducing government jobs considered a free lunch?

Politicians love to brag about cutting government work forces.  This month, while the private sector added 57,000 jobs, government shed 39,000 jobs, for total job growth of 18,000, which is basically not different from zero statistically.

Cutting government jobs not only has consumption effects (people who don't get paychecks can't buy stuff), it also has productivity effects.  When the DMV is closed three days a month, people have to wait longer to get their drivers' licenses.  When there are fewer cops, crime increases.  When there are fewer high school teachers, the ability to offer AP courses drops, etc.

Is there waste in the public sector?  Sure.  But for those working in the private sector, particularly large institutions, ask yourself whether everyone you work with is productive.  I have no idea what the "correct" level of public sector employment is.  I also have no idea how much public sector employment crowds out the private sector, but if the crowding out effect is less than one (and with unemployment above nine percent, I am guessing the effect must be less than one), then reducing government employment reduces total employment.  But to think that cutting government employment is a magic pill for economic recovery makes no sense.


Wednesday, July 06, 2011

What is the incidence of the Fannie-Freddie bailout?

There is lot of rending of garments and gnashing of teeth that the FF bailout will cost something like $300 billion, including the implicit subsidy to mortgages that are guaranteed (the cash flow cost right now is something like $130 billion).  So for an economy whose GDP is roughly $14.5 trillion, this is a little more than two percent of GDP.

To whom does the money go?  Given that shareholders were essentially wiped out, it goes to largely three places: holders of Fannie and Freddie debt, the US Treasury (which owns preferred shares in the companies) and homeowners.  I am curious how this shakes out distributionally.  Clearly, homeowners are on average richer than renters, and bondholders are richer than non-bond holders, so the bail-out must have some regressive implications, but it is not clear to me how much so.  It is at least worth thinking about.


Tuesday, July 05, 2011

So Congressman, how do you get to 19 percent?

From Mark Thoma's blog, I pick up the following quote from Paul Ryan:

RYAN: What happens if you do what he’s saying, is then you can’t lower tax rates. So it does affect marginal tax rates. In order to lower marginal tax rates, you have to take away those loopholes so you can lower those tax rates. If you want to do what we call being revenue neutral … If you take a deal like that, you’re necessarily requiring tax rates to be higher for everybody. You need lower tax rates by going after tax loopholes. If you take away the tax loopholes without lowering tax rates, then you deny Congress the ability to lower everybody’s tax rates and you keep people’s tax rates high.
The Congression Budget Office did an analysis of the Ryan Budget plan, which anticipates revenues rising to 18.5 percent of GDP by 2022 and to 19 percent by 2030.  Revenue is currently at 15 percent (Table 1 on page 3).   The CBO followed the following instruction:

The path for revenues as a percentage of GDP was specified by Chairman Ryan’s staff.
The path rises steadily from about 15 percent of GDP in 2010 to 19 percent in 2028
and remains at that level thereafter. There were no specifications of particular revenue
provisions that would generate that path. (see page 11).
If Ryan will only accept closing loopholes in order to cut marginal tax rates, partcularly for the wealthiest Americans, I am hard pressed to see how we get from 15 to 19--would you care to specify Congressman Ryan?
 
I was on a panel last month with Ryan, and was impressed with how intelligent he is, particularly in contrast to Wisconsin's governor.  The fact that he is so intelligent tells me that he knows what a cynical game he is playing.

Kurt Paulson adds more evidence that FF were not leaders into the crisis

 ).
From comments:
I think there is at least one additional and important piece of data in support of your argument which, to my mind, has been underplayed in this whole discussion. FHFA released a research report in Sept. 2010 entitled "Data on the Risk Characteristics and Performance of Single-Family Mortgages Originated in 2001 - 2008 and Financed in the Secondary Market." Of particular importance is Figure 8 (page 16), entitled "Ever 90-Day Delinquency Rates on Higher Risk Single-Family Mortgages Originated from 2001 through 2008 and Sold into the Secondary Market, by Origination Year." While not a great title, the graph shows that for Higher Risk loans, PLS default rates were ALWAYS higher than GSE loans for vintage 2001-2007 loans. A frequently repeated claim is that the GSEs (whether or not through their "affordable" goals) caused a reduction in underwriting standards and therefore caused the crisis. As you point out, this is false - despite some bad actions by the GSEs. What this Figure 8 demonstrates is that it PLS defaults for similarly situated borrowers were substantially higher. Private securitization cannot be blamed entirely for the crisis: but it cannot be excused. These data seems to suggest that PLS underwriting was worse than the GSEs. The report and data can be found at: http://www.fhfa.gov/Default.aspx?Page=313 (but I can't seem to link to the Figure itself).

Monday, July 04, 2011

Mark Thoma and Dean Baker are correct: Fannie Mae and Freddie Mac did not start the crisis.

Rather they followed it.  The data showing how private label securities led us into the mess is here.  Mark Thoma and Dean Baker take down the Will-Brooks-Morgenstern-Rosner meme that in the absence of Fannie and Freddie, we would not have had a financial crisis.

Did Fannie and Freddie behave admirably?  In many respects no, but they did maintain underwriting discipline longer than most of the rest of the mortgage market.  On the other hand, their bad behavior from early in the decade prevented them from leading the market: accounting scandals (Freddie understated earnings while Fannie overstated them) led the companies' regulator, OFHEO, to require both companies to improve their capital ratios, which meant they needed to shrink their share of the mortgage business.

The most disturbing part of the attacks on the GSEs is that it is an indirect method for blaming minorities and the poor for the financial crisis, an argument that is at once ludicrous, disingenuous, and reprehensible. (Once again, I should disclose that I worked for Freddie from September 2002 until January 2004.  I should also note that the fact that I stayed there for such a short period reflects in part a lack of particularly warm feelings for the company.  I do own a few hundred worthless shares of Freddie Mac stock).


President Obama and Regulation vs. Pricing

I opened my New York Times this morning to see that President Obama wants to raise fuel economy standards by twofold over the next 14 years.  I have no doubt that the goal of reducing fuel consumption is a good one, but doing it using regulation is clumsy and could be counterproductive.

First, such regulations could hurt welfare in three ways: if it drives up production costs, it will reduce the number of cars sold and hence have an adverse impact on employment.  Second, it could lead to cars that people don't want, and so consumer welfare is reduced.  Third, if cars get high mileage, people will drive them more--not enough, in all likelihood, for total fuel consumption to go up, but enough to create other negative externalities, such as congestion.

But what of the fact that fuel consumption produces negative externalities?  That it leads to greenhouse gas emissions and  endangers our security?  The best way to deal with a negative externality is to impose a Pigou tax--one that requires consumers to pay for both the private and social costs of their actions.  If the US had gas prices more similar to what we observe in other parts of the developed world, it is likely that people would generally choose more fuel efficient cars, but that those who wanted big cars even in the face of higher gas prices would be able to buy them.  At the same time, such a policy would discourage driving (better fuel economy encourages driving), and would therefore help relieve congestion a bit.  The revenue raised by a gas tax could also be used to fund transit and provide a tax cut to those most hurt by higher gas prices--those at the lower end of the income distribution.


Friday, June 24, 2011

Does it make sense to build "affordable" housing in Santa Monica?

Among the people I admire most in the urban research business is Marjorie Turner.  I was talking to her at a conference sometime within the last year, and she put a difficult question to me: shouldn't housng policy allow everyone who wants to live in Bethesda, Maryland the opportunity to do so?  (Bethesda is among Washington, D.C.'s most affluent suburbs).

I have been pondering this question for some time, and it was thrown into relief for me when I witnessed a person bragging about building affordable housing units at $650,000 a pop in Santa Monica.  The presentation brought me around to the view that it is not society's responsibility to assure that everyone gets to live anywhere they like, just as it is not society's responsibity to buy everyone a Mercedes Benz (a night on the town every now and then might be something else).

Every household should have the opportunity to live in a clean, safe community with a decent school.  For this reason, expanding the Section 8 housing vouchers program, which allows low income households to rent market rate housing while paying no more than 30 percent of income, would make a lot of sense.  Given the fiscal realities of the moment, a sensible source for funding an expansion would be the Low Income Housing Tax Credit Program--a program that funds $650,000 properties in Santa Monica.

The median price of a house in Los Angeles County is around $275,000.  The median neighborhood in LA County is a fine neighborhood.  So one could put someone in a decent house and a decent neighborhood and still have $375,000 left over relative to Santa Monica.  That $375k could go toward better schools, more transportation options--or more housing! 

Do I wish everyone who wanted to live in Santa Monica could do so?  Sure.  I also wish everyone who wanted to take a vacation to Paris could take a vacation to Paris.  But when resoureces are scarce and getting scarcer, it is important to use them as effectively as possible.

Thursday, June 23, 2011

Do bond holders think it is all political theater?

The GOP pull-out of the budget talks today really worried me--it raises my subjective probability of a US default, which would be potentially catastrophic.  But when I looked at long-term bond prices on Bloomberg, they suggest the bond markets are completely calm.


Tuesday, June 21, 2011

How well off are Americans?

As Alice Rivlin notes, tax increases on the rich (which are, in my view, necessary and, in light of recent changes in income, appropriate) are not enough to bring about long-term fiscal balance (the short run is another matter--fiscal tightening at the moment makes no sense to me).  So the question is, in the long term, how far down the income distribution should we go when we ask Americans to sacrifice?

An OECD report, Growing Unequal? Income Distribution and Poverty in OECD Countries, provides country ranks for average income for ten income deciles.  For the top four deciles, seven, eight, nine and ten, Americans earn more than their counterparts in all other countries, save Luxumbourg, a country whose population is about the same as Dane County, Wisconsin.  For the next decile down, only people in the Netherlands and Luxembourg have higher average incomes.  One could argue, then, that anyone in the top five deciles is pretty well served by being an American.

Things turn a little worse after that: the fifth decile ranks five; the fourth ranks 6, the third ranks 10th, the second ranks 14th and the bottom decile ranks 19th!  In light of this, it seems reasonable to say that the median and below is about the place where we might not wish so ask for more sacrifice.

(BTW, thanks to my USC student Sarah Mawhorter for digging the data out of the report for me).

Alice Rivlin on the Budget (h/t Mark Thoma)

She writes:

Republicans worry that spending caps will threaten national security and Democrats that domestic needs will suffer. Both need to recognize that not all government money is well spent. Democrats are terrified of entitlement reforms and Republicans of tax increases, but there will be no solution without some of each. On entitlements, Democrats have to accept that the status quo is not an option and Republicans that draconian benefit cuts are not acceptable. On revenues, Democrats have to recognize that the debt can’t be stabilized just by taxing the very rich; the middle class will have to contribute too. Republicans have to recognize that in the face of a rapidly increasing older population, it is undesirable to hold spending at historic levels, so we need more revenues. Both parties should recognize that entitlements and earmarks in the tax code are the same as spending, and phasing them out can enhance growth.


No way out?

At a Rand meeting yesterday, Stuart Gabriel called housing the "tail that wags the dog" of the US economy.  He was likely referring to this paper or, perhaps, this paper.  In any event, the evidence from past business cycles powerfully supports residential construction as a leading indicator.

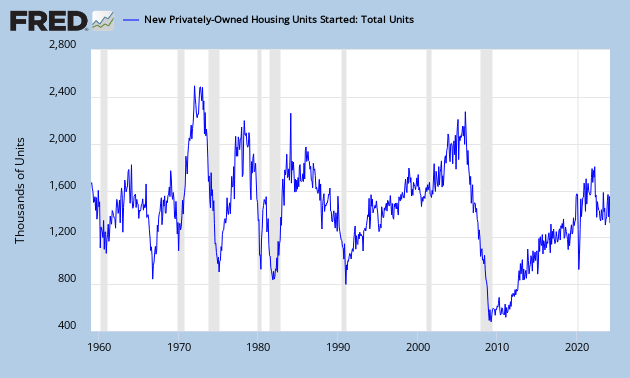
Here is the St. Louis Fed's depiction of housing starts going back to 1959:


In an average year, the US economy starts around 1.5 million houses.  It has started fewer than 600,000 per year since 2008, and is currently squiggling along at a bottom unprecedented in the St. Louis Fed series.

I find it hard to see how the economy can recover strongly without housing making a comeback.  Yet we still have too many houses--builders cannot compete with the inventory currently available. While they try to differentiate new houses from stuff in the foreclosure stock, it is tough to make a sale when price differences are very large.  The problem is that stimulating housing is a bad idea too, because we really don't need many more houses in the economy right now.  As my colleague Gary Painter points out, one of the reasons we don't need more houses is that household formations dropped dramatically--we actually lost households early in the recession while population grew.  Moreover, according to the Department of Homeland Security, illegal immigration dropped by 2/3 between 2000-2004 and 2004-2009.  Whatever one thinks about immigrants (personally, I like them), they do fill up houses.

We are left with a quandary.  For the economy to be restored to health, housing construction needs to return to normal--but there is no reason for it to return to normal.  The alternative--waiting--doesn't seem very appealing either.


Monday, June 20, 2011

There are days when it is hard to be a liberal

This afternoon I heard a woman say with a straight face that Santa Monica is committed to affordable housing.  This was after she bragged about the low density, high design standard, affordable housing that Santa Monica built.  What was the construction cost for the project?  More than $600,000 per unit--because each unit uses a lot of land, which is expensive in Santa Monica, and because of those "high design standards."

The median price of a house in Los Angeles County is about $300,000.    When a subsidized housing unit costs $600,000, the average person is implicitly paying a lucky family to live in a nicer than average house.  This is of course inefficient--it also undermines the consensus necessary to make sure everyone is housed adequately.

We do indeed have a huge problem in Southern California--many families do not have sufficient income to afford a reasonable unit in a location close to a job.  Building gold plated housing in Santa Monica does not help solve the problem.


Sunday, June 19, 2011

Places that voted for Obama have longer-lived women

The Washington post featured a story about life expectancy for women and men by county. The data come from the University of Washington's Institute for Health Metrics and Evaluation, and in particular a paper by Sandeep C Kulkarni, Alison Levin-Rector, Majid Ezzati and Christopher JL Murray.


The Post story contained a fun interactive map, and I could not help but notice that "blue" places appeared to have longer lived people. I couldn't help myself, so I downloaded data on elections from Mark Newman's website at the University of Michigan. Specifically, I downloaded data on the 2008 presidential vote by county.

I then drew a scatterplot in Stata of Obama's share of the Obama-McCain vote against women's life expectancy:


Again, the unit of observation is county.  The size of the dots reflects total votes by county.  The vote weighted correlation between women's life expectancy and share of Obama vote is .262, which is not insubstantial for a bivariate correlation.

One cannot draw any causal inference from any of this, of course, and my guess is that the Obama vote share is proxying for something else--perhaps educational attainment.   But drawing these pictures is fun (BTW, the correlation for Obama vote and men's life expectancy is a smaller .168).

In preparing a talk on the history of US Housing Policy, I found this...


Notice that it is serious and fairly lengthly, and was done by local TV news.

Two Newspaper articles prompt the question "when is enough, enough"

The Washington Post has a nice piece (that relies on a study by Jon Bakija, Adam Cole and Bradley T. Heim) about how executive compensation has been the principal driver behind the increasingly unequal income distribution in the United States.  It uses Dean Foods as a nice case study---the current CEO (who apparently runs the company well) makes ten times the income of the CEO from the 1970s (who also ran the company well).  One reason for the difference is that Kenneth Douglas, the 70s era CEO, turned down pay-raises, arguing that it if he made more than is $1 million per year, it would be bad for morale.

Immediately after reading this article, I read another in the Milwaukee Journal-Sentinel about the search to replace Biddy Martin as chancellor at the University of Wisconsin-Madison.  In that article, Jan Greenwood, a presidential search consultant is quoted:


UW-Madison "is a phenomenal university" with world-class status, said Jan Greenwood, a presidential search consultant.
But, "Wisconsin, at this point in its history, is one of the states that is having severe challenges because of compensation issues," she added.

Martin made $437,000 per year plus benefits plus a fully staffed large house.  One can live very well in Madison for $437,000 plus a house.  That is enough to take nice vacations, eat out wherever one wishes, and drive a nice car.  It is probably even enough for owning a boat or small plane if such things really mattered to someone.

Maybe my problem is that I am a homer--I got my Ph.D. in economics at Madison and then was on the business school faculty there for twelve years.  The place does have some serious issues, but is also quite extraordinary.  Getting to run it while being paid enough to enjoy lots of consumption seems like a pretty good deal to me.

Friday, June 17, 2011

As I watch people drive...

..I can't help but think about a problem with the Euler Equations for consumption.  Young people (especially young men) do dumb things on the road that can get themselves killed in much larger numbers than old people.   This is not just anecdotal, because insurance statistics back this up.  (Also, as one who drives in LA, my N for making this inference is pretty large).

But of course as we approach our cap T, we should be taking on more and more risks, because the expected losses get smaller and smaller.

Sure, the u(c(t),t) function can change with t, but then it also becomes sort of useless.


Thursday, June 16, 2011

Program note

I will be on Bloomberg tomorrow talking about foreclosures.  I look forward to the day when no one wants to talk to me about foreclosures.  

Monday, June 13, 2011

Stephen Malpezzi on "Sifting and Winnowing"

My longtime co-author, colleague and friend's opening remarks to last week's Wisconsin Real Estate conference has been mischaracterized, so I am reproducing the entirety of those remarks here:


I'm very proud to be associated with this conference. I want to thank all the speakers and presenters, and especially all of you in the audience, for making this conference a success.


The Wisconsin Idea tells us that the University needs to be connected to real problems and issues faced by Wisconsinites as well as those beyond our physical borders, in the rest of the nation and indeed around the globe. It is our basic job description. As I look over the agenda I think we've put together a meeting that does meet the test of the Wisconsin Idea.

Two years ago we changed the name of our annual conference from the Wisconsin Housing Conference to the Wisconsin Real Estate and Economic Outlook Conference, to recognize the deep connections among housing, other kinds of real estate, and the economy in general.

Over the next few years, as Morris Davis provides the academic leadership for the Graaskamp Center and Mike Brennan leads our connection to the industry, I'll be spending part of my time to strengthen the focus of the Graaskamp Center on economic development.

Details will follow in the months ahead. Today I want to simply bring this effort, and indeed this conference, back to the touchstone of "sifting and winnowing" that is part of our inheritance from our intellectual and institutional forbearers, beginning with Richard Ely. Most of you have heard the phrase, and many of you have seen the plaque atop Bascom Hill, from a century ago:

Whatever may be the limitations which trammel inquiry elsewhere, we believe that the Great State University of Wisconsin should ever encourage that continual and fearless sifting and winnowing by which alone the truth can be found. Taken from a report of the Board of Regents. 1894 [slide of the plaque projected]

As many of you know, this quotation, famous on campus and off, came out of afierce debate about (of all things) unionization, in 1894. In brief, Ely supported unionization, and some of the Regents did not. They never, to my knowledge, reached agreement on the specific issue, but they did, in the end, establish a firm principle that at Wisconsin, people had a right to speak on different sides of important issues; a right to be heard; and that we owe those with whom we disagree, as well as those with whom we agree, a duty to listen.

To be clear, "sifting and winnowing," doesn't mean that every idea is equal; but rather that ideas should be heard, and examined on their merits, rigorously, rather than reflexively. As Daniel Moynihan famously put it some years ago, everyone is entitled to their own opinion, but not their own facts. Sifting and winnowing helps us establish the facts, and helps us form opinions that are grounded in those facts as well as our values.

Now, in light of the principle of sifting and winnowing, today we aim to have some constructive conversations about housing, real estate, and our state's economic development.

I'm a professor, and I do research on these subjects. But economic development is not simply an abstraction, or merely an academic subject. It touches all of our lives, and our children's lives. Economic development is not just about economics, not just how much stuff we can produce or buy. It's also about how well housed we are, whether we're educated to reach our full potential, how well we attend to our health. It even touches on our basic security, and at the national and global level, questions of war and peace.

The key to understanding economic development is to start by understanding there is no key to economic development. There is no silver bullet. Economic development is complicated.

Unfortunately we live in a world where simple solutions get the headlines. All too often, we talk past each other, cherry picking research and arguments that support our preconceived notions, and ignoring research that challenges our preconceptions. Psychologists call this confirmation bias, and it's a very powerful part of human nature. We're all subject to it. We have to fight it, every day. The best way to fight confirmation bias is to hold to rigorous standards of evidence, and hold your own opinions to the same standard to which you hold others.

For example, if you're a Republican, or a fiscal conservative of whatever persuasion, you might think state tax cuts are a silver bullet. It's important that you know about the substantial body of research that tells us simple tax differences between states explain virtually none of the variation in state economic performance.

To pick another example, if you're a Democrat, or someone who worries about providing enough resources to schools, you might think that more dollars to our schools, perhaps for smaller class sizes, are a silver bullet. It's important that you know that of a number of careful studies done on this issue, so far I've only found one that finds statistically significant relationships between class size and performance, and that only in a few grades. Most careful studies are unable to find a simple relationship.

I can list another dozen silver bullets that aren't really silver. School vouchers, charter schools, passenger rail, spending on roads, less regulation of business, more regulation of business.

It gets even more complicated here. None of these is a silver bullet. None, by itself, are magic beans that take us up the stalk to Economic Development Nirvana. Yet each of these ideas contains some germ of truth, or at least can help us think harder and better about what kinds of things are likely to work, and in what combination. Tax cuts can help if we find ways to preserve essential services while reducing taxes. As a society, we haven't had that conversation yet. Some charter schools, and some public schools, do work as advertised; we need to make sure we figure out why, and replicate and encourage them. As a society, we haven't had that conversation yet. It's not about how much regulation we have so much as what kind of regulation, how we make regulations and taxes and other government interventions smarter. As a society, we haven't had that conversation yet.

Recognizing that some of the best ideas will come from people with whom you disagree, is an important step towards making these true conversations, productive conversations. We need, as Ely and the 1894 Board of Regents taught us, to sift and winnow. Fight your confirmation bias; help me see mine, but in a constructive way. Don't paint yourself, or others, into corners. Determine the facts, and what works, without regard to ideology; and then act on it.

This is why we are here today. Join us in a day of sifting, of winnowing, of learning. Let's move these conversations forward today. Listen, as well as talk. Do recognize that, if we're honest and careful about it, sometimes we'll initially be uncomfortable with what we find. Challenge yourself as well as others. Let's move the conversation ahead, not only today, but over succeeding weeks and months and years. Let's get Wisconsin's economy, and our people, moving FORWARD.

On Wisconsin!


Sunday, June 12, 2011

Congressman Ryan and I agree about three things

Much to my surprise, during our time on a panel together in Madison last Thursday, I found him to be less of an ideologue than I expected.  I will continue to disagree with him on a "premimum support" system to replace Medicare, and I don't think his budget adds up (he never says how he gets revenues to 19 percent of GDP or discretionary spending down from 12 percent to 3 percent).  Still:

(1) He and Julia Coronado (another economist on the panel) said that increased life expectancy meant that we should raise the retirement age for qualifying for social security.  I said I agreed except for the fact that simply raising the retirement age could be regressive, given that lower income people have shorter life expectancy.  Julia said this could be fixed with different indexing for different income levels.  Congressman Ryan suggested allowing blue collar workers, whose bodies take more punishment than those of us in cushier jobs, to retire earlier.  I was pleasantly surprised at this.

(2) I suggested that regulation should be based more on metrics than fiat.  In particular, I suggested robust a meaurable capital standards for banks, and Pigou taxes for banks as they increased in size.  He said he liked the idea of regulation based on metrics, and he did not agure my point about Pigou taxes.  He also went out of his way to note that large financial institutions have the ability to capture their regulators.

(3) We were all asked to name someone with whom we often disagree who has changed thier mind about something.  Congressman Ryan named Alice Rivlin.  I can thing of many worse people to name.

He was also extremely well prepared to answer questions spontaneously, and even cited academic studies to support some of his points. 

Wisconsin Governor Scott Walker's speech at the event, on the other hand, did nothing to improve my opinion of him. 

Sunday, June 05, 2011

What are basic economic principles?

Whenever someone says that all policy problems can be solved by markets, they appeal to something they call "basic economic principles."

If one goes to the open course page for the intermediate micro course offered at MIT, one finds the following topics on the syllabus:


Consumer Theory
2Choice, Preferences, Utility
3Demand, Revealed Preferences, Comparative Statics
4Consumer Surplus, Aggregation
5Variations to the Basic Choice Model (Time, Uncertainty)
Producer Theory
6Technology, Profit Maximization, Cost Minimization
7Supply, Aggregation
Markets
8Monopoly
9Oligopoly and Game Theory
10Walrasian Equilibrium
Market Failures
11Externalities
12Public Goods
13Small Number of Agents, Nash Bargaining
Asymmetric Information
14Adverse Selection, Moral Hazard, Principal-Agent Model
15Auction Design
16Voting and Other Applications
Six out of fifteen of topics (8-9, 11-14) are about ways the market can produce suboptimal outcomes.  These topics are not esoteric any more (they are showing up in intermediate courses), and they have rigorous economic theory behind them.  It was time we stopped using the phrase "basic economics" to refer to idealized market conditions that often do not exist.


Saturday, June 04, 2011

A principle for deficit reduction

As I am preparing for a panel on the US budget I will be participating in on Thursday in Madison, a principle occurs to me.  Given that over the past 30 years the economy has disproportionately benefitted high income people far more than low income people, and holders of capital more than earners of wages, any deficit reduction proposal should be, on net, progressive, after considering both changes to the tax code and expenditures.  This is not easy to do analytically, and could still involve some sacrifice from most people, but it should at least be a point of departure.